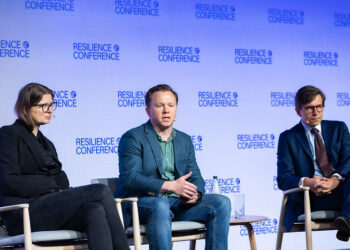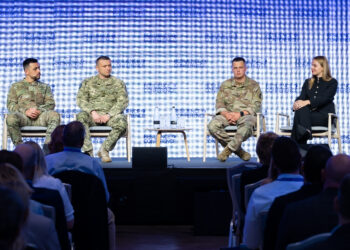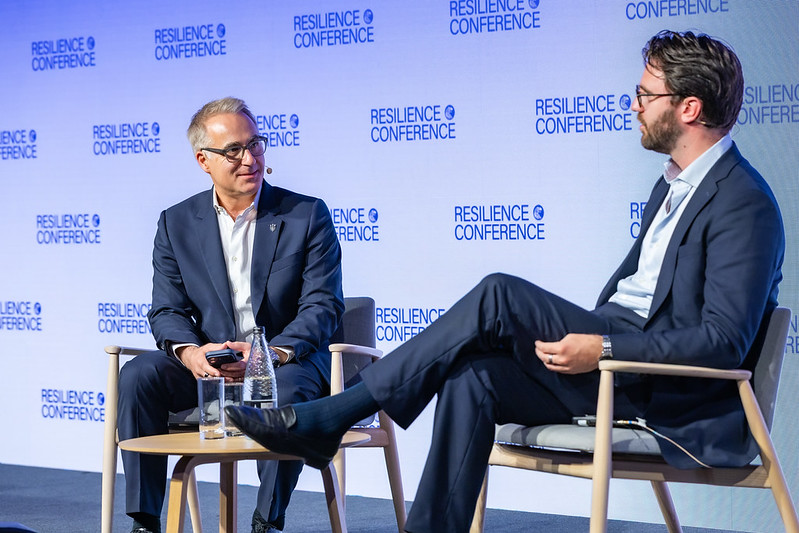
Lakestar’s Chris Magazzeni (pictured above, right) sat down with Resilience Media editor-in-chief Tobias Stone during our London conference in October, to discuss trends that could define the European defence tech industry in the years to come.
Magazzeni’s message was that after the outpour of startup solutions responding to the rapidly evolving challenges of modern warfare, now has come time for consolidation. States only look for “two to three suppliers, maximum, for given products,” he said, adding that in the defence sector “governments historically have only a handful of relationships, they’re not going to suddenly have hundreds, so [the consolidation] is inevitable.”
According to him, the current question is whether “this period of consolidation happens at some point with greater acceleration of the course over the next 18 months.”
He said that the pace of this process depends on three factors: first, “the competition with other funds that have raised money and are trying to keep [defence tech startups] independent for longer,” second: “whether or not a neo-prime will try and snap it up to avoid being beaten to the chase and swallow the increased price or just wait until that period,” and finally, whether neo-primes will take over smaller companies, rather than their main competitors, “in order to cement its position as having, within that vertical, something to be able to offer the customer.”
If it’s not survival of the fittest, then it’s survival of the most scalable. The governments will select its contractors, said Magazzeni, based on “who can deliver at scale.” Lakestar’s estimation is that Europe will eventually end up with 5 to 10 neo-primes, “probably not that much more.”
A crucial question for European defence tech founders is whether the race to become a continental leader is still on. While new frontiers keep opening, according to Magazzeni, “we are seeing the momentum of capital rushing towards a couple companies now that seem to be pulled away from the rest. You can just look at who has raised 500 million, a billion, in the last six months. The number of companies is quite small.”
A possible trap that the emergence of a handful of European neo-primes brings is whether they will not behave like legacy defence companies, losing some of their agility and ability to innovate.
For Magazzeni, European governments should follow the lead of Ukrainian policies to prevent that from happening: “at the end of the day, companies follow the incentive that the customer places on them, and if we don’t know the lesson from Ukraine, I think there’s a serious risk of that.”
Other insiders present at Resilience Conference agreed with the Lakestar investor: PJT Partners’ Gwen Billon also predicted “more M&A and consolidation.”
The past months have already shown signs of this process taking place. Only in September, UAS producer Stark announced that it had acquired an electronic warfare startup Raydiant RF, and Tekever took over Scottish Flowcopter.